“Investing is a wonderful, thoughtful, adventure but it can also be self-centered, a tendency that can be reinforced by the wealth that can follow. We think it is true that, once past X-amount, real meaning comes with reinvesting in society through charitable giving, which can also be a thoughtful, challenging, wonderful adventure, but with the added bonus that it feels like the world working properly. We hope that you can join us.”
Nicholas Sleep and Qais Zakaria, 2021.
I just finished reading the entire saga of Nomad Partnership (From 2001 to 2013 Nomad returned 20.8% CAGR before fee). It was an amazing avventure, worth the time reading the 218 pages which compose the letters written by Nicholas “Nick” Sleep during his adventure.
Avventure is the word Sleep uses often describing his journey through 13 years of investing. To contextualize, Nick and Zak were early investors in Costco and Amazon. These letters were written every six months, from the end of 2001 to early 2014, and sent to Partners in the Nomad Investment Partnership. The fund through this period generated a wealth of 2bn USD.
I suggest you read the entire collection in order to appreciate the deep meaning of the investing journey.
This discipline goes beyond the simple research of money, but it encompasses the whole spectrum of human existence, passing through psychology, history, charity, adventure and discovery.
Nick Sleep itself named it as “Our adventures in capitalism”.
Sometimes we research adventure in sci-fi movies or Netflix series, on top of that I find this a more interesting adventure, an adventure into the real world, an adventure which puts yourself to become a better thinker and more knowledgeable about our reality. Free market, in this sense, is a feedback machine. We use our brain to formulate hypotheses, and the market assesses our hypothesis.
Like all adventures, an adventure hides dangers, but even great opportunities to become free and enlightened, more creative, and more productive. Free time for yourself, over and above that, for our family and for the entire humanity.
The purpose of this blog is to journal my personal adventure, as a diary, where I share what I learn, and the path I trace. Charity and philanthropy are always capital allocation activities, as they are investing in the stock market, but oriented to humanitarian purposes.
As in the Sleeps’ case , indeed Nomad Partnership ended in 2014, and today Nick Sleep is active in the philanthropic field through the I.G. Foundation.
In the investing section of their website you can find the entire collection of letters.
The letters
source: https://igyfoundation.org.uk/
I will try something unconventional, I will chronologically reverse the narrative, starting from the end to the beginning, because, as I explained in the blog, with a healthy goal in mind, it will become easier to forecast the bad days of our investing journey.
THE GOAL
“…we had what we needed, just a few superb businesses, and we were unlikely to sell any of those to fund the purchase of another cigar butt, Philippine cement company, were we? The pull was the prospect of independence and a new adventure, this time working out how to recycle the funds for others to benefit. We wound up at an age (mid 40s) when it forced us to build something new (you can’t sit on the beach forever), and, hopefully, we would live long enough to also see the consequences of our actions; we would have to eat our own cooking, as it were. Previous generations that retired in old age and died soon after, have not always had that opportunity. As we said in the preamble, we have not entirely left investing behind either.
…
Investors can think their way to success without seeming to work in the traditional sense and the payoff in capitalism from stock picking can be extraordinary. It is one thing for capital allocators to be rewarded for their efforts but, in our opinion, taking personal identity in everything above X-amount is not a route to building a better world. We suspect that: if you made it to the end of our letters, then you are one of the good guys and know that already. If good investing is a minority sport, then good philanthropy is a minority sport for those that do minority sports. Our band could do with moving from the fringes of society to becoming the norm. We hope you will join us on the journey.”
Nomad Letters by Nicholas Sleep
“You are the Hero of your own Story”
Joseph Campbell
I rearranged the remaining key concepts in three main categories:
Herd Bias and Market
Short Term Attitude
“The hero is tempted to abandon or stray from his quest. Traditionally, this temptation is a love interest, but it can manifest itself in other forms as well, including fame or wealth.” Margaret Atwood
Creativity and Thinking
Wisdom and Self-Learning
Behavior
Value Investing
Portfolio Management
Global Diversification
Cash
Business Valuation
Management Valuation
“A hero ventures forth from the world of common day into a region of supernatural wonder: fabulous forces are there encountered and a decisive victory is won: the hero comes back from this mysterious adventure with the power to bestow boons on his fellow man.” Joseph Campbell
Amazon
Costco
Dell
WalMart
AirAsia
Quotes from Nomad Partnership Letters by Nicholas Sleep and Qais Zakaria
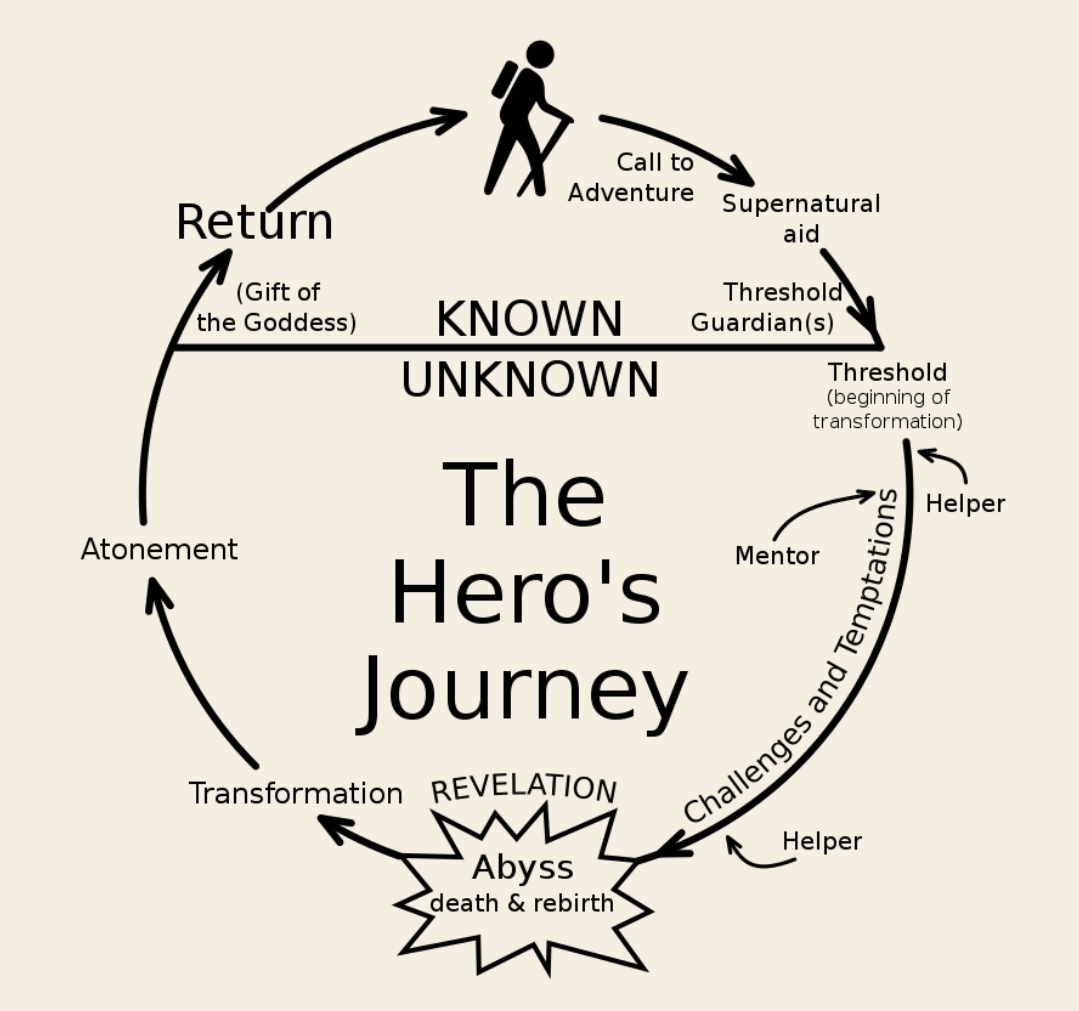
Every adventure begins with a protagonist who lives in the ordinary world, and receives a call to explore uncharted territories, full of risks and uncertainty. An seemingly impossible venture for a common man. For that reason the protagonist is usually helped by a mentor (The Helper) who gives him a light in the dark (Principles and Tools), and a dose of courage to abandon the herd and take responsibility for his own journey. Lastly the helper warns the protagonist about the journey’s dangers (Temptations). There is a hero inside of everyone, and for everyone of us there are virtuous mentors. This article is dedicated to two of my heroes who became mentors, as a result of the accomplishment of their own adventures (Cases Study).
“If I have seen further it is by standing on the shoulders of Giants”.
Isaac Newton
The next are thoughts and quotes written by Nicholas Sleep and categorized by me in a non-chronological order. Sometimes, you will find quotes of other great investors reported by Sleep in his letters, besides I inserted a few of my thoughts highlighted in italic font.
Temptations: PSYCHOLOGY
Herd bias and Market
“If Zak and I bring something to the investment party, and I may be stretching things a little here, it is to be more rational than other investors. At least, we hope that is the case.”
“So, patience, social proof, vividness and probability-based thinking are the four psychological hurdles I have chosen to highlight and I think we understand these perhaps a little better than the average investor out there…”
“One of the reasons that Nomad is Nomad is that Zak and I spend 213 almost no time thinking about stock market indices.”

“Following what everyone else is doing may be hard to resist, but it is also unlikely to be associated with good investment results. Zak and I concentrate on the price to value ratio of the Partnership and ignore its performance as much as is practical, and we would encourage you to do the same.”
“Traditional economists argue that people are rational beings who seek, what economists call, utility maximization, that is, the maximum output for any one input. This old guard are hostile to assertions of non-rational behavior, perhaps because the idea that we are all rational is just so elegant. Scientist and External SFI Professor W. Brian Arthur argues that this static, equilibrium-based model of the world does not sit easily with the biologist’s view that individuals act in self-interest, make mistakes, learn and evolve. Or the psychologists’ view of the world that there are systematic biases to individual decisions – that is, we have these little wobbles in our decision-making processes. Arthur describes the economy as a Complex Adaptive System that evolves as agents (people) learn.”
“…the dominant dynamic in the markets today [2002]: investment time frames are very compressed, and few investors it seems bother to assess the real value of a business but instead respond to the latest data point to determine share price direction. This is momentum investing and is the mechanism by which expensive shares become very expensive, just as cheap shares may become very cheap.”
“When there is a frenzy of activity in one area of the market there is very often an anti- bubble of discarded companies. In the dot com era these were companies with steady cash flow”
“When we wrote to you a year ago, we said, “It may not feel like it but for a long term investor this is the best of times not the worst [GFC 2008]…Take heart and look to the horizon.” Today we have a portfolio of exceptional, iconoclastic businesses that we could own for many years. “
“Companies often misclassify their mistakes in terms of outputs rather than inputs, and in so doing allow the original mistake to go unchecked. Psychologists call this denial, and we all do it to some extent. “
“denial, that is the reinvention of reality in the mind because the truth is too painful to bear; anchoring, that is a static, historic vision of a problem; and drift, that is how small, incremental changes in thinking build into a big mistake. Add judging to the list as well, in the sense of condemning or exalting: that disposition stops a lot of rational thought, and it is almost ubiquitous”
“It is not easy because there are so many distractions: news items, the soap opera of the stock market, macroeconomic events, politics, currencies, interest rates, principal/agent temptations, regulation, compliance, administration and so on – this list is not exhaustive! It is all too easy to make things more complicated than they need to be or, to invert, it is not easy to maintain discipline. One trick that Zak and I use when sieving the data that passes over our desks is to ask the question: does any of this make a meaningful difference to the relationship our businesses have with their customers?”
“a greater risk to our businesses may come as a by-product of success – be it bubble valuations in the stock market and/or, political risk in the form of anti-trust like pressures.
…
the long-term risks our companies face are not those that dominate the newspapers and headlines today (credit crises, housing crises, budget crises, Euro crises and so on) but those events that could prevent them from reaching their potential.“
“A word of warning: the current market [Dec 2004] is not like the end of the 1990s when a bubble in high priced mainly technology stocks was balanced with Zen like symmetry by an antibubble of cheap, slower growth business. Today, prices are evenly high across the various opportunity sets, and there are few readily apparent pockets of under-valuation of size. We particularly enjoyed an editorial in the Investor’s Business Daily carried in December, which captures the mood of the markets quite well
“The Fed tightens, stocks go up. The dollar falls, stocks go up. Oil soars, stocks go up. Retail sales wobble, stocks go up. Is this a great country or what?”
“It is probably fair to say that reinvestment risk (the risk from investing the incremental dollar poorly) is probably higher today than normal. But then, with the Partnership closed, we do not have many incremental dollars to reinvest. “
“Bill Miller argued that there are three competitive advantages in investing: informational (I know a meaningful fact nobody else does); analytical (I have cut up the public information to arrive at a superior conclusion) and psychological (that is to say, behavioural). Sustainable competitive advantages are usually a product of analytical and or psychological factors, and the overwhelming advantage with regard to Nomad is the patience of the investor base and the alignment of that disposition with the analytical and psychological traits of your manager. It simply would not work otherwise. In the investment objective section of the Nomad prospectus, we say that our job is to “pass custody [of your investment] over at the right price and to the right people” and that “the approach will require patience”. That’s what investing is, at least for us.”
“we have no idea where the market will end this year but given corporate strategies, capital allocation and starting valuations, I think we have some idea of how our companies will evolve over the next few years. In other words (at this point economics students may wish to cover their ears) the return from investing in shares can be both increased and de-risked by time.”
“Well Brian Arthur at the Santa Fe Institute refers to the economy as a complex adaptive system that learns as agents learn. And that seems like a way better model to me… “
“Non-transitive dice offer two handy investment models: first, just as any dice can win for a while, so any superiority an investment process may have will only emerge with time, so patience is important. Second, the stock market posts prices every day, this is the equivalent of making your opponent chose his dice first.”
“In a traditional capital cycle framework, the high valuation of these businesses encourages a supply side response, which eventually undermines the economics discounted in the stock price.
…
Indeed, human nature being as it is, we can almost guarantee that capital spending will continue to grow until share prices decline.
…
For such stocks to be a viable investment for Nomad we would have to feel confident that sector economics are not discounted in prices several years out and, given the rise in capital spending plans, that is not the way to bet. And this is Nomad’s great strength. By looking out five years we do not have to invest in shorter-term phenomena in order to look good this year. And in our opinion that is at the heart of what is driving the frenzied trading in Phelps Dodge – the desire to look good this year, quarter, month, week, or just today. When there is a frenzy of activity in one area of the market there is very often an anti- bubble of discarded companies. In the dot com era these were companies with steady cash flow. “
“Operating inside the bubble, it is hard for many participants to see this. The author Upton Sinclair, commenting on the attitude of businessmen and almost one hundred years to the day before the current credit crisis, had it about right, “it is difficult to get a man to understand something when his salary (or bonus) depends on his not understanding it”. So, the mindset is prevalent because it pays in the short term. But this does not make it the right thing to do, nor does it make it profitable over the long-term. “
“Investors know that in time average companies fail, and so stocks are discounted for that risk. However, this discount is applied to all stocks even those that, in the end, do not fail. The shares of great companies can therefore be cheap, in some cases, for decades.”
“The insanity of bubble-like valuations was well captured by Scott McNealy in a 2002 interview in Business Week when he was still CEO of Sun Microsystems (source: James Montier, Société Générale, Cross Asset Research Group), “But two years ago we were selling at ten times revenues when we were at U$64. At ten times revenues, to give you a ten-year payback, I have to pay you 100% of revenues for ten straight years in dividends. That assumes I can get that by my shareholders. That assumes I have zero cost of goods sold, which is very hard for a computer company. That assumes zero expenses, which is really hard with 39,000 employees. That assumes I pay no taxes, which is very hard. And that assumes you pay no taxes on your dividends, which is kind of illegal. And that assumes that, with zero R&D for the next ten years, I can maintain the current revenue run rate. Now, having done that, would any of you like to buy my stock at U$64? Do you realize how ridiculous those basic assumptions are? You don’t need transparency. You don’t need footnotes. What were you thinking?”
Short-Term attitude
“So ,for example, the biggest mistake an investor can make is to sell a stock that goes on to rise ten -old! ‘ not from owning something into bankruptcy. But that’s what everyone thinks,”
“In previous Nomad letters we have argued that the biggest error an investor can make is the sale of a Wal-Mart or a Microsoft in the early stages of the company’s growth. Mathematically this error is far greater than the equivalent sum invested in a firm that goes bankrupt. The industry tends to gloss over this fact, perhaps because opportunity costs go unrecorded in performance records.”
“…far better, Zak argues, to earn less, but for a much longer time”
“In our opinion, transient, historic, stock price quotation volatility is not the same as investment risk. Indeed, quite the opposite.” Ed. Beta an academic gift to us
“As ever, a stoic indifference to these short-term steps, both up and down, is the right way to think,”
“ At Marathon a full holding cycle can exceed 5 years, so any quarter individually considered could be poor without affecting long-term outcomes. For those keen on monthly results there will be 60 such data points in a full holding cycle. These data points, in the hands of an inexperienced investment committee, could be misconstrued or worse. After all, most of Marathon’s client termination events occurred after, rather than before, a period of underperformance. This is clearly what can happen via the mark-to-market effects of quarterly reporting. The “Pavlovian” association of poor short-term results with long-term incompetence and confusion between the two can lead to disastrous decisions.”
“Good investing is a minority sport, which means that in order to earn returns better than everyone else we need to be doing things different to the crowd. And one of the things the crowd is not, is patient.”
“We can all do momentum investing, but it is emotional investing and I just don’t think it is that intelligent, or profitable.”
“Immediate gains are perceived positively compared to larger deferred gains as the limbic (survival) system has the ability to over-ride the fronto-parietal (analytical) system. Interestingly, stress induces this over-ride, and of course, money induces stress. So, the more stressed we are, the more we value short-term outcomes! This is not without reason, for if starving is a real possibility, a meal today is more important than a feast in a week’s time, and the brain’s wiring reflects that survival bias.”
“The quality of our research-based decisions overwhelmingly determines whether we will do well in the long run. But it has almost no influence over the timing of these results. Zak and I do not control the annual performance figures. It might be nice if we did. But we don’t. “
“The lag that often exists between investment decision and eventual reward is a problem for long-term investors, as the brain is wired to learn from immediate feedback. The biological presumption (and, as mentioned in the last Nomad letter, the academic presumption too) is that cause and effect sit chronologically on top of each other – after all, you would want to know that the plant you have just eaten is poisonous now (so you can stop eating it) rather than in a week’s time, when it would be too late.”
“the equity yield curve is a concept that argues that patience has a value, and that returns increase with time in the equity market as they do on a normal bond market yield curve.”
“So, the more stressed we are, the more we value short-term outcomes!”
“As a result, Keynes warned, the stock market would become ‘a battle of wits to anticipate the basis of conventional valuation a few months hence rather than the prospective yield of an investment over a long term of years.…Simply put, what went wrong was a pathological mutation in capitalism—from traditional owners’ capitalism, where the rewards of investing went primarily to those who put up the capital and took the risks—to a new and virulent managers’ capitalism, where an excessive share of the rewards of capital investment went to corporate managers and financial intermediaries.”
Jack Bogle
“We have learned or, rather, come to appreciate, that the character of a firm – call it the ability to resist locker room temptation – is far more important than first we realised. This is an important insight. In the long run it may be all that matters.
It is perhaps 170 the dominant, get-ahead mindset of our times and it is inherently focused on vivid, short term outputs.
…
This is an attitude whereby the players just have to win, and they are not too squeamish about the means. And if winning, for some, meant securing a bigger bonus than others, then, in the case of the mortgage market, any way to get people to buy expensive paper was just fine, and to hell with the consequences. This is a proud, manipulative, points-scoring orientation that manifests itself in all walks of life, but may be especially evident on Wall Street, although some salesmen, sportsmen, chief executives, politicians, warlords and hedge fund types are notably not exempt.”
“Alternatively, the second way to invest is to buy shares in a great business at a reasonable price and let the business grow. This appears to require just one decision (to buy the shares) but, in reality, it requires daily decisions not to sell the shares as well! Almost no one does this, in part because it requires patience – and the locker room set does not do patience – but also because inactivity is the enemy of high fees.”
““Don’t just do something, stand there!”
The White Rabbit, Alice in Wonderland
…
The research continues but, as far as purchase or sale transactions in Nomad are concerned, we are inactive.”
“Investor Conference Bill Miller, whose investment skills we much admire, confessed to analysing his mistakes more thoroughly than his successes. The latter he automatically presumed to have gone up for the very reason the shares were bought. As investors we all do this to some extent, winners flatter the ego regardless of the reason they went up, whilst we all feel bad about the losers. Several academic studies argue that mistakes hurt up to three times more than gains satisfy, a product of primordial environmental conditioning designed to prevent us from repeatedly eating poisonous food, apparently. For investors the implication of this asymmetry is great as it is often the favorable outcomes that drive performance more than losers destroy it.”
The Helper: PRINCIPLES Life and Investing
Creativity and thinking
“Investing in stocks is an art” Peter Lynch (11. Stories and Number)
“After a recent speech Gell-Mann was asked, “So, how do you have creative thinking?” His answer was: 1. Start thinking about something, gather data to the point of saturation, recognise anomalies and recognise that you are now stuck; 2. Retreat and simmer, mull it over and a period of incubation ensues with the unconscious mind deployed; 3. Whilst doing something else a solution to the problem surfaces (Archimedes’ eureka revelation); 4. Go and verify the new solution. To Gell-Mann, taking time is important in creative thinking.”
“the frontal cortex of the brain, which is charged with rational thought and information processing, can make more sense of the world, given enough time to think it through, than the senses themselves can make sense of the world. “
“And then there are the differences, for instance information does not always have food-like quality standards. There is little-to-no labelling of information presented on television, so fact and fiction can be deliberately fused and have given rise to “docudramas” and “mocumentaries”. In literature the same phenomenon exits and has been popularised following the success of books such as Dan Brown’s “The Da Vinci Code”. To avoid confusion, one solution may be to label information for its fact content, in the same way we label food for its fat content.
…
Information, like food, has a sell by date, after all, next quarter’s earnings are worthless after next quarter. And it is for this reason that the information that Zak and I weigh most heavily in thinking about a firm is that which has the longest shelf life, with the highest weighting going to information that is almost axiomatic: it is, in our opinion, the most valuable information. No doubt Charles Darwin would agree.”
Wisdom and self-learning
“Discovery is one of the joys of life and, in our opinion, is one of the real thrills of the investment process. The cumulative learning that results leads to what Berkshire Hathaway Vice-Chairman Charlie Munger calls “worldly wisdom”. Worldly wisdom is a good phrase for the intellectual capital with which investment decisions are made and, at the end of the day, it is the source of any superior investment results we may enjoy.”
“Behavioural Finance takes a pragmatic, multidisciplinary approach (a little like Geography!) and puts the rational economists’ view of the world together with that of the psychologist and biologist. After all, how can economics not be behavioural.”
Behavior
“As Darwin found, it is hard to let the facts speak for themselves, reject the established way of thinking and to do so in good conscience.”
“it is not the money you have, but the choices you make, that count.”
“Good things follow when you care about the pennies.”
“People don’t care about the pennies anymore, that’s why no one has got any money,”
“We keep our discussions to as high a level as we can manage in the belief that, in the long run, the high level is all that matters. In these letters we have therefore discussed business models, incentive compensation, capital allocation, mistakes, more mistakes, even more mistakes, lots on psychology and how to think, lots on attitude and so on.“
“Nassim Nicholas Taleb (author of “Fooled by Randomness”) published an interesting paper (free, on the internet) which also linked the sequence in which returns occurred to how they made investors feel. He argued that investors often accept the risk of an occasional large loss for a steady small profit as the recurrence of the gains made them feel better. This occurred even when an opposite strategy, of steady small losses followed by a large gain, generated superior end results. Travelling comfortably dominates people’s thinking when they should be thinking about destinations.”
“As a younger man I separated investing from the rest of my life, as if they were different worlds. This is a false construct. Another mistake. What we learn from home-life helps us be better investors, and what we learn as investors helps us be better husbands and fathers. In the end, all reality has to respect all other reality.
And that’s what a full life is all about. Thank you for your support. “
“From time to time we swap slippers for brogues and head out into the world with the expectation that what we learn through investing helps us in other activities outside the office, and what we learn doing other activities helps us as investors.”
“If Nomad is to have a competitive advantage over our peers this will come from the capital allocation skills of your manager (if any) and the patience of our investor base. Only by looking further out than the short-term crowd can we expect to beat them.
(The term patience appears 49 times in the letters)”
“1.Misanalysis, or using the wrong mental model: Investors are used to firms which have one good idea, such as a new product, but then struggle to replicate success and end up diluting returns (Zak and I call this the Barbie problem, as Mattel has struggled to replicate the economics of its famous doll). Taking this model and applying it to Wal-Mart would miss the company’s source of success entirely as the strategy of price givebacks did not change from year to year; culture plays a part in the continuity of a successful price giveback strategy and factors such as culture, because they are hard to quantify, often go undervalued by investors;
2. Structural or behavioral: Active fund managers have to look active. One way to do this is to sell Wal-Mart, which appeared expensive (but actually wasn’t), to buy something that appeared cheaper (but err, also wasn’t); investors are not long-term and did not look further than the next few years or, more recently, few quarters. Evidence for this can be gleaned from the average holding periods for shares which stands at just a few months;
3. Odds or incorrectly weighing the bet: In the words of my first boss,
Empirical Research Partners, an investment research boutique, discovered that the chance of a growth stock keeping its status as a growth stock for five years is one in five, and for ten years just one in ten. On average, companies fail.”
“[In the mid 1960’s]“a very famous collector, who has one of the finest noses for sniffing out a deal, hears a whisper that the first James Bond Aston Martin DB5 may be for sale…The word is that for the right money, the original James Bond car can be bought directly from the movie studio. So he makes a few calls, he tracks down the production guy… “It’s gonna have to be 15 for the pair” “You mean there are two?” “Hey man this is show business, there is always two… at least” “But 15 for the pair” says our man. “I wasn’t counting on spending that much and I don’t really want two – I just want one” “When that is the deal. Take it or leave it.” …“Fifteen thousand pounds – a lot of money now, a load of money then. Our hero hesitates for a moment, but his nose knows better. It tells him to deal. He buys the car. The cash is to be paid on delivery of both vehicles. The day arrives, the trailer pulls up, the cars roll off. The invoice reads: FIFTEEN HUNDRED POUNDS. Yes, friends both original Bond cars for £1500, but it does not end there. Be prepared to run for the hills screaming. Our man then swaps one of the Bond cars for a GTO. That’s a GTO for £750. That’s the cheapest GTO ever and…he still has it today.”
…
We are reminded of Winston Churchill’s story of a man on his deathbed: I have had a lot of trouble in my life, says the dying man, most of which never happened. It may not feel like it but for a long-term 156 investor this is the best of times not the worst. It is in this environment that people sell their GTOs for £750. Take heart and look to the horizon.”
“Even though consumers were being offered what seemed to Schwartz to be an ever-increasing plethora of choice to meet their needs, he could find no correlation with increased happiness. Instead, he hypothesised, that with all the choice came the (subconscious) expectation that the outcome ought to be perfect, and this expectation rendered the actual choice made as disappointing in comparison. It was as if too much choice was making us unhappy.
…
It is very easy, therefore, to feel unhappy about one’s investments. Indeed, on any one day, month, year it is highly likely, indeed statistically almost certain, that one’s chosen combination of investments will lag alternatives – there will always be someone who did better. In a recent Nomad letter (June 2010) we wrote… “Readers that make it to the end of our letters (we may be flattering ourselves), including the footnotes (we may be deluding ourselves!), may recall the story we retold of the Ferrari 250 GTO bought by a collector in the 1960s for the effective price of £750. The beauty of the story is that although the car is one of the most valuable in the world, the collector still has his car today. A different 250 GTO has recently changed hands, and the price…US$20m!”
Value Investing
“Finally, it is the long-term investor, he who most promotes the public interest, who will in practice come in for the most criticism, wherever investment funds are managed by committees or boards or banks.
If he is successful, that will only confirm the general belief in his rashness; and if in the short run he is unsuccessful, which is very likely, he will not receive much mercy. Worldly wisdom teaches that it is better for reputation to fail conventionally than to succeed unconventionally.” Source: The General Theory of Employment, Interest and Money John Maynard Keynes
“And what did we learn in Investing 101 from Lord Keynes: “better to be generally right than precisely wrong”! At the time we were making these errors we would have held Keynes’ quote as true. One has to be so careful; sometimes these mistakes are very insidious. Keynes’ dying words were reported to be “I should have had more champagne”. No doubt he is right on both accounts. Destination analysis is consciously central to how we analyse businesses these days. It helps us ask better questions and get to a firm’s DNA. What we learnt at Conseco may well have kept us out of the US banks last year, and what we learnt at Stagecoach has helped us continue to own Amazon”
“In the 1960 letter Buffett writes: “I have pointed out that any superior record which we might accomplish should not be expected to be evidenced by a relatively constant advantage in performance compared to the Average. Rather it is likely that if such an advantage is achieved, it will be through better-than-average performance in stable or declining markets and average, or perhaps even poorer-than-average performance in rising markets.”” (Annex Fig. 1,2)


Fig 2,3. Warren Buffett compounded at 22% from 1968 to 2012, underperformed the S&P 500 one out of every three years during that run.
Source Summit Street Capital Management
“I have pointed out that any superior record which we might accomplish should not be expected to be evidenced by a relatively constant advantage in performance compared to the Average. Rather it is likely that if such an advantage is achieved, it will be through better-than-average performance in stable or declining markets and average, or perhaps poorer-than-average performance in rising markets”
“Good investment process is not apparent in one quarter’s worth of transient stock price quotations, or one year for that matter!”
“The prime determinants of outcome are price (sticking to 50 cents on the dollar) and capital allocation by management. The first is in our control, that is, it is in our control to be patient and wait for the right price. The second involves a subjective judgment about the quality of management, and an assessment about the sustainability of business returns in the long run. It is these factors that occupy almost all our time. “
“Our aim is to make investments at prices we consider to be fifty cents on the dollar of what a typical firm is worth. Capital allocation by investee companies must be consistent with value creation and, if this is the case, we expect that the real value of the business (the 100 cents value) could grow at around 10% per annum. The effect over five years will be to compound U$1 of value into U$1.62, and companies that can build value like this are normally rewarded in the market with a fair valuation (i.e., are priced close to U$1.62). This happy outcome would imply a return from purchase price (50 cents) of around 26% per annum. So, what happens when we are wrong? Our most common mistake is to misjudge capital allocation decisions by our companies: firms which articulate a share repurchase/debt repayment strategy and have incentives to reinforce that outcome, throw caution to the wind and make acquisitions instead. The Partnership’s investment in Readers Digest falls into this category. Capital allocation mistakes such as these often prevent the compounding of value but to date have rarely resulted in a permanent decline in the share price to below our purchase price (50 cents). We have therefore tended to find that our mistakes atrophy (stay cheap) rather than collapse, although we can all name one collapse!”
“The debate over growth and value is perennial, and quite unnecessary. Warren Buffett got it right years ago: “Whether appropriate or not, the term “value investing” is widely used. Typically, it connotes the purchase of stocks having attributes such as a low ratio of price to book value, a low price-earnings ratio, or a high dividend yield. Unfortunately, such characteristics, even if they appear in combination, are far from determinative as to whether an investor is indeed buying something for what it is worth and is therefore truly operating on the principle of obtaining value in his investments. Correspondingly, opposite characteristics – a high ratio of price to book value, a high price-earnings ratio, a low dividend yield – are in no way inconsistent with a “value” purchase.” Source: Berkshire Hathaway 1992 Annual Report
We won’t end the debate here but, so that we all understand,
Growth is therefore inherently part of the value judgment, not a separate discipline.
…
and why do commentators continue to use price to book ratios, price to earnings ratios or their modern equivalents such as EV to Ebitda, as a proxy for value. We all know that it does not mean a thing. So why do we do it?
…
However, in the stock market, doing half the work (only observing a portion of the wardrobe) is of limited benefit if successful investment requires more work. Price to book, price to cash flow etc., cannot be an accurate substitute for the definition we provided above.
Their informational value, leaving aside inaccuracy for a moment, can be limited if only because successful investing is a minority sport. Their survival can probably be attributed to intellectual laziness on the part of the investment professional, and spin on the part of the industry’s marketing departments. It certainly has little to do with investment excellence.”
“It is worth noting also that the Partnership results have been achieved without leverage, shorting or financial derivatives of any kind, nor do we wish to employ such techniques. Rather our results have been achieved the old-fashioned way, through buying securities in reasonable businesses at discounted prices.”
“If the share price is being set by those with an eye on the next data point, then they can’t also be looking out for long-term value. There are few traders that disagree with Bezos’ value creation process, but they don’t think it will show up in the numbers just yet. And if you only own shares for a month or two then you may get away with several trades before Amazon’s success becomes apparent.
Good luck to them. Picking up pennies in front of a juggernaut is just not how we behave. “
Portfolio Management
“It may also be worth reiterating that the results have been achieved without leverage, shorting, contracts for difference, options, synthetic structures (LYONs, PRIDEs, LEAPs, MASTs – we are not making these names up) or financial exotica of any sort. … and the results below have been achieved without the investment Viagras that have become so popular with the get-rich-quick-crowd. The results have been earned the old-fashioned way, through contrarian stock picking.”
“ We have ended up with a portfolio of owner-managed businesses as a byproduct of our assessment of the quality of the people involved. In other words, these managers earned their way into the portfolio. We feel slightly foolish for not recognizing this trait in advance, but, of course, we would have a bias toward founder-managed businesses (duh!). “
“The problem of course is price. In paying up for excellent businesses today, investors are already paying for many years growth to come, in the hope that, as the saying goes, “time is the friend of a good business”.
Those that chase high prices today, leave less gunpowder for the future.”
“Even though prices are generally high, the trick is to do the work today, so that we are ready.”
“Our portfolio inaction continues and we are delighted to report that purchase and sale transactions have all but ground to a halt. Our expectation is that this is a considerable source of value added!
…
but we do know that the average time S&P500 constituent stocks have been included in that index is twenty-five years.
…
As Berkshire Hathaway Vice-Chairman, Charlie Munger, says, you make your real money sitting on your assets!”
“Costco’s obsession with sharing scale benefits with the customer makes that company’s future much more predictable and less risky than the average business and that is why it is our largest holding. Our smaller holdings are less predictable but in certain circumstances could do much better as investments. We are just not sure that they will as their “cone of uncertainty” has a much greater radius than at Costco. “
“So, what you are trying to do as an investor is exploit the fact that fewer things will happen than can happen.”
“Zak and I expect that we have built a portfolio not just for the recovery out of recession but for many years after that too. At least, we aim for such a Zen-like state.”
“In reality opportunities in which we are comfortable to deploy capital are rare, and the highest conviction ideas the rarest of them all. The issue then is how much to invest in each idea? Bill Miller, who has run the Legg Mason Value Trust so brilliantly for many years, suggests the use of a system devised in 1956 by J. L. Kelly. A simplified version of the Kelly criterion is that investors should bet a proportion of the portfolio equal to 2.1 x p – 1.1, where p is the probability of being right. The common-sense outcome of this equation is that if one is certain of being right, one should invest the entire portfolio in that idea. Even if one is say, 75% certain of being right the correct weighting remains high at 47.5% ((2.1 x 0.75) – 1.1). But does anyone do that?
But is this not the right way to think? If you know you are right, why would you not bet a high proportion of the portfolio in that idea? The logical extension of this line of thought is that Nomad’s portfolio concentration has at times been too low. And if it has been too low at Nomad, what has been going on at the large mutual fund complexes with many hundred stocks in a single country portfolio? Apply the Kelly criterion, and the average fund manager would appear to have almost no clue as to the likely success of any one idea.
If you do not share this view, think long and hard about your investment in Nomad.”
“…the best defense is to own enough of the company to influence the outcome. In most cases in excess of 10% of the shares outstanding would suffice. Those that advocate market liquidity of their investments over other considerations might like to bear in mind an investor’s inability to influence outcomes whilst owning a de minimus proportion of a company. Should Nomad continue to grow in size, we intend not to make this mistake”.
“The church of diversification, in whose pews the professional fund management industry sits, proposes many holdings. They do this not because managers have so many insights, but so few! Diversity, in this context, is seen as insurance against any one idea being wrong. Like Darwin, we find ourselves disagreeing with the theocracy. We would propose that if knowledge is a source of value added, and few things can be known for sure, then it logically follows that owning more stocks does not lower risk but raises it! Real diversification is offered by index funds at a fraction of the price of active management. Sam Walton did not make his money through diversifying his holdings. Nor did Gates, Carnegie, McMurtry, Rockefeller, Slim, Li Ka-shing or Buffett. Great businesses are not built that way. Indeed, the portfolios of these men were, more or less, one hundred percent in one company and they did not consider it risky”
Global diversification
“The geographical distribution is as follows: south east Asia 32.8%; North America 23.6%; Europe 12.7% and other emerging markets 2.9%.”
“Geographically the distribution is as follows: US 41%, Hong Kong 14%, UK 12%, Thailand 9%, South Africa 6%, Malaysia 5%, and Norway and Singapore 4% each.”
“Investors are often guilty of chasing the new-new thing far from home sometimes in the name of diversification, or higher returns, or both. To our way of thinking such activity often has more to do with marketing than it does with underlying investment reality.”
Cash
“And for most of the decade, there has been nothing as sinful in an investor’s mind as money idly slouching on deposit, “on the couch” as the investor Seth Klarman put it. Instead, cash must be put to work: its yield maximised.
…
Output maximisation looks efficient at least in the short term, but that is not the same as being long term optimal. The flaw to putting money to work immediately, for instance, is to presume that all relevant opportunity sets are available immediately. By accepting, say, a promoter’s promise of eight percent returns (six hundred basis points better than money on deposit), the investor denies himself the right to future opportunity sets which may be far better, like public equity circa 2008 and 2009, we would argue.
…
It is, however, an argument for a cash buffer, just in case, a little slack in the system.”
Business Valuation
“return on capital at Nomad’s firms is over twice that of competing businesses.”
“we try to take Charles Darwin’s approach: deemphasise the data collection and think. When we study truly great businesses, we find that very often it has been simple human attributes that have led to their success: you feel differently drinking a Coke than a no brand cola or, you may feel differently towards a business that consistently undercuts the competition in price or, a delivery service that literally goes the extra mile and picks up returned items – and the reason you have these feelings, and the stimuli that produce them, have hardly changed in millennia.”
“What characteristics could one bestow on a company that would make it the most valuable in the world? What would it look like? Such a firm would have a huge marketplace (offering size), high barriers to entry (offering longevity) and very low levels of capital employed (offering free cash flow).”
“A business ought to be able to self-fund its own growth, and if the opportunity set is large, then the return on capital needs to be suitably high. Second, barriers to entry should increase with size; that way a company’s moat is widened as the firm grows. To do this, the basic building block of the business, its skeletal structure, is probably best kept very simple. In short, we want a skeletal structure that can support growth from mouse to elephant without too much skeletal reengineering.”
“When we evaluate potential investments, we are looking for businesses trading at around half of their real business value, companies run by owner-oriented management and employing capital allocation strategies consistent with long term shareholder wealth creation.”
“The answer lies in analyzing not the effects and outputs of a business, but, digging down to the underlying reality of the company, the engine of its success. That is, one must see an investment not as a static balance sheet but as an evolving, compounding machine. “
“When looking for an explanation to a situation the brain tends to latch on to what can be easily found to “frame” the situation, and if what is easily found is also vivid, then the brain stops looking for another explanation. I had gone looking for what I thought ought to be there, a vivid smoking gun such as a brand name, a location, a clever re- insurance contract, or a patent. However, there is no a priori reason why a comparative advantage should be one big thing, any more than many smaller things. Indeed, an interlocking, self-reinforcing network of small actions may be more successful than one big thing.
…
firms that have a process to do many things a little better than their rivals may be less risky than firms that do one thing right because their future success is more predictable. They are simply harder to beat. And if they are harder to beat then they may be very valuable businesses indeed”
“it was the success and economics of line extensions (incremental products) and advertising that, in our opinion, was what the long-term investor really needed to embrace.
…
Recognising and correctly weighing this information in spite of the latest news flow is a matter of discipline, and it is that discipline that is so richly rewarded in the end. The simple deep reality for many of our firms is the virtuous spiral established when companies keep costs down, margins low and in doing so share their growing scale with their customers.
…
“There are two ways to build a successful company. One is to work very, very hard to convince customers to pay high margins [the Colgate, Nike, Coca-Cola model alluded to above]. The other is to work very, very hard to be able to offer customers low margins [the Wal-Mart, Costco, AirAsia, Amazon, Asos model]. They both work. We’re firmly in the second camp. It’s difficult – you have to eliminate defects and be very efficient. But it’s also a point of view. We’d rather have a very large customer base and low margins than a small customer base and higher margins.” “
Jeff Bezos”
“So, having shared low costs with their customers, how are our firms’ relationships with their customers going? One way to look at this is revenue growth.“
“Souter began cutting away the weak businesses, a process Charlie Munger, vice Chairman of Berkshire Hathaway refers to as the “cancer surgery approach”. This often works because there is normally a jewel at the heart of most companies that has often been used to fund new ventures or is taken for granted by impatient management. As the jewel becomes diluted by less successful projects aggregate performance declines and valuations atrophy or even fall. The star in this regard and in which Mr. Munger invested, is Coca-Cola, which in the mid 1980s had become a poorly defined conglomerate including a shrimp farm, winery, film studio and shudder to think, even owned its own bottling plants! As the poorer businesses were cut away, to reveal the jewel that is the syrup manufacturing and marketing operation, the shares of Coca-Cola rose over ten-fold in the succeeding decade. At Stagecoach the fix is relatively simple: cease investment in poor US operations,”
“For these investments to work over the long haul, what is required is a rational, honest mea-culpa and a low share price. The unforgiving nature of the markets often provides the latter. The former is much harder to come by.”
“If the market was rational and the company an organisation that learns, then the stock price should rise after a mistake.”
“Depersonalisation inevitably leads to customer disloyalty and commoditisation, and that is not good for long term profitability, regardless of what the profits account reads today.”
Management Valuation
“Our first shareholder letter, in 1997, was entitled, “It’s all about the long-term”. If everything you do needs to work on a three-year time horizon, then you’re competing against a lot of people. But if you are willing to invest on a seven-year time horizon, you’re now competing against a fraction of those people, because very few companies are willing to do that. Just by lengthening the time horizon, you can engage in endeavours that you could never otherwise pursue. At Amazon we like things to work in five to seven years. We’re willing to plant seeds, let them grow – and we’re very stubborn. We say we are stubborn on the vision and flexible on the details”.
Jeff Bezos
“Almost ninety percent of the portfolio is invested in firms run by founders or the largest shareholder”
“Fifty-five percent of portfolio companies are either repurchasing shares or have had meaningful insider buying.”
“There are only two reasons companies behave well. Because they want to, and because they have to. Our preference is to invest in those that want to.”
“Math-based decisions command wide agreement, whereas judgment-based decisions are rightly debated and often controversial, at least until put into practice and demonstrated. Any institution unwilling to endure controversy must limit itself to decisions of the first type. In our view, doing so would not only limit controversy – it would also significantly limit innovation and long-term value creation”. Jeff Bezos
“Early in a firm’s development it makes sense to reward customers disproportionately as customer referrals and repeat business are so essential to the development of a valuable franchise. With maturity this bias can be reduced, and shareholders can reasonably take a greater slice of the pie. Too much, however, and the moat is drained with negative consequences for longevity. The temptations are enormous because capital markets will reward profiteering.”
“What passes for industry standard best practice today may look short term efficient but, in any lasting sense of the word, and from the perspective of the long-term business owner, it does not really get the job done.”
“If the existing portfolio is to be successful then our results will come from the mismatch between the orientation of the founders and the mark to market mentality of the quarterly holding period investors that set the price of the companies on the stock market. “
“All the social pressure will be to conform with industry norm but these companies have a deep keel that keeps them upright. “
““if you want to be successful, and we do, then you have to be willing to be misunderstood, and do things that do not seem sensible to most people.
We start with the customer and work backwards”
Founder of one of Nomad’s investee firms
…
In other words, his company had an internal compass with true north pointing to what was right for the customer.
…
Zak and I would guestimate that fewer than five percent of publicly listed firms do what they think is right, rather than what they think plays well with the outside world (media, Wall Street, investors). Even so, the vast majority of Nomad’s firms do what is right long term.”
“The same is probably true for Jim Sinegal before his retirement (Costco), Lord Harris (Carpetright) and some of the other founders of the firms in which Nomad has invested. These people derive meaning from the challenge, identity, creativity, ethos (this list is not exhaustive) of their work, and not from the incentive packages their compensation committees have devised for them.
…
It was an arbitrary number in the first place, and we derive a great deal of value from the meaning of the work we do (challenge, sense of job well done, identity, creativity and so on) not just from the financial rewards (although we will learn to live with those too!). By having an attitude that is somewhat independent of financial rewards, we are sure that Nomad’s performance in the long run will be far better too.”
“Zak’s family’s activity centre beat the competition because they understood the difference between good costs (nice staff, clean loos, good coffee) and bad costs (a whizzo new slide) and invested appropriately. They were smart enough to poll customers and observe the influence of pricing (there was no need to over-discount). The operation was equity funded and did not include a third party in the capital structure (bank debt). But most of all it was founder managed and they cared. Watching the pennies and investing carefully has led to the “aggregation of marginal gains” and financial success, and as such it has much in common with the investments that populate Nomad. It has been fun for Zak and me to practice in the real world, what we preach in investing.”
“In the office we keep a list of companies assembled under the title “super high-quality thinkers”. This is not an easy club to join, and the list currently runs to fifteen businesses. Entry is reserved for the intellectually honest and economically rational, but that alone is not enough. There are many companies that do the right thing when their backs are against the wall, and this list excludes those temporarily attending church. The anointed few are there because they have chosen to out-think their competition and allocate capital over many years with discipline to reinforce their firm’s competitive advantage. Good capital allocation takes many forms and does not necessarily require a firm to grow.
…
After all, why grow if returns are going to be poor? However, surprisingly few companies have the strength to just sit it out, or shrink, as
The clamor comes from within the company (reinforced by poorly constructed incentive compensation), Wall Street promoters and short-term shareholders.”
The Helper’s journey: CASES STUDY
Amazon
“Our businesses are surging ahead, even if, in some cases, their share prices are half what they were twelve months ago. In the last few months Amazon has been priced in the market as if it would not grow in the future, despite some of the best growth prospects we can imagine.”
“However, our quantitative understanding of elasticity is short-term. We can estimate what a price reduction will do this week and this quarter. But we cannot numerically estimate the effect that consistently lowering prices will have on our business over five years or ten years. Our judgment is that relentlessly returning efficiency improvements and scale economies to customers in the form of lower prices creates a virtuous cycle that leads over the long-term to a much larger dollar amount of free cash flow, and thereby to a much more valuable Amazon.com.”
Jeff Bezos
“Amazon.com may be following this path as well. So, the first point is that whilst Costco continues to recycle cost savings to the consumer, it is lowering the probability of failure. So, what heuristics do investors incorrectly apply to Costco (why might the shares be mispriced?). Heuristic One: “the company has low margins” (net profit margin is 1.7%, compared to Wal Mart at 3.6% and Target at 4.2%). True, but that’s the point. The firm is deferring profits today in order to extend the life of the franchise.
Heuristic Two: “it’s expensive at 24x earnings”. Really? Net income is a small residual, as discussed above.
Heuristic Three: “Costco has a cost problem”. Costs have risen as a percentage of revenues in the last few years due to the expense of a warehouse and distribution system associated with the next phase of the firm’s growth and the cost of employee benefits and insurance, especially in California.”
“Bezos was also quite forthright on the subject of product promotion and advertising at this year’s annual general meeting: “Advertising is the price you pay for having an unremarkable product or service”.
“Amazon.com. Last year the company reported free cash flow of just over U$500m, indeed it has been around this number for the last few years. What is important is that the U$500m is after all investment spending on growth initiatives such as capital spending, but also research and development, shipping subsidy, marketing and advertising and price givebacks. “
“Amazon, for example, is choosing “not to participate” in as much as trailing twelve- month revenues have risen by over sixty percent since the onset of the credit crisis, say mid 2007. Not that the steady growth in revenues has always been apparent in its stock price, as the chart below describes. As a youthful analyst I used to have a notice on my desk that read, “share prices are more volatile than corporate cash flow, which is more volatile than asset replacement cost”. It was reminder to concentrate on non-transitory items. Today I would update such a notice to read, “share prices are more volatile than business values”, but the gist is the same: a reminder to focus on lasting value, not transitory prices. “
“Our hunch is that the growth rate in online retailing is regulated, not by physical capacity, although that can be a limiting factor, but more by the rate at which our own incumbent habits and associations are replaced with more rational behaviour.
…
if the rate of growth in internet retailing is a product of attitude, rather than assets, then, the fact that a firm is quite large already does not necessarily tell you that its growth rate is set to slow”
Costco
“At Costco, the consumer has chosen to commit to the retailer. In other words, people shop at Costco because it is Costco, not because Costco stocks Coke. And the reason they shop is that goods are priced at a fixed maximum 14% mark up over cost.
Costco must ensure that: (1) Operating costs are low, indeed very low. It is indicative of the paranoia with which the company is run that costs are measured in basis points (there are 100 basis points in one percentage point)
(2) That the wholesale price is as competitive as can be.
“We expect all vendors to consistently and voluntarily quote the lowest possible acquisition price available on all items. A vendor who does not consistently and voluntarily quote its lowest prices to our buyers will be permanently discontinued as a purchasing source for Costco.” Source: Costco.co.uk
(3) Revenues need to be very high
Costco is the best example we can find of one of them: scale efficiencies shared. Most companies pursue scale efficiencies, but few share them. It’s the sharing that makes the model so powerful.”
Indications are that the company is gently tinkering with the division of benefits in favour of shareholders in part to satisfy the quarterly EPS junkies but also in recognition that an asset-rich Costco represents an attractive target for private equity buyers. Long-term shareholders should view such slippage as worrying and unnecessary. In our view, the correct response to a six-year share price famine is for the company to use its balance sheet to buy back shares at prevailing prices and allow the long-term growth in free cash flow per share (an inescapable function of steady margins, falling asset intensity, growing revenues and a shrinking base of shares outstanding) to translate into a higher share price over time.
Dell
“Michael Dell succeeded by keeping costs low and passing back his scale benefits to the buyer of his PCs”
“A study by Michael Goldstein at Empirical Research, a research boutique, claims that 49 the probability of growth stock failure (company growth slowing) is as high as four in five over five years and nine out of ten over ten years. And in the case of Dell, we would have been wrong.”
Walmart
“Although we are all interested in margin, it must never be done at the expense of our philosophy. Margin must be obtained by better buying, emphasis on selling the kind of goods we want to sell, operating efficiencies, lower markdowns, greater turnover, etc. Increasing the retail prices and justifying it on the basis that we are still “competitive” could lead to a rude awakening as it has with so many. Let us concentrate on how cheap we can bring things to the people, rather than how much the traffic will bear, and when the race is over Fed-Mart will be there”. [The best summary of the business case for scale economics shared we have come across].
Sol Price, Fed-Mart’s founder
“in the 1950s a large Baltimore based fund management company sold their clients’ shares in IBM only for the shares to appreciate to the point that the value of the shares sold would become bigger than the whole fund management company itself. What we are trying to do today is avoid the Baltimore company’s second mistake, which was to sell an equally big stake in Wal-Mart in the 1970s!” (Fig.4)
Fig 4. Wal-mart

“In our opinion, the central engine of success at WalMart was a thrift orientation fueling growth with the savings shared with the customer.
…
Instead, investors may place too much emphasis on valuation heuristics, or margin trends, or incremental growth rates in revenues or any of the list above, but these items are transitory and anecdotal in nature
…
Put simply: average companies do not do scale economics shared. Average companies do not have a healthy culture.
…
It is a huge anomaly that investors recognize success incrementally when the factors that lead to success, such as scale economics shared reinforced by a strong culture, may be constant. “
AirAsia
“Take Air Asia: The firm was born with a no frills, cost culture with the result that, we estimate, it is the lowest cost airline in the world: this is favourable branch one. Favourable branch two: the employees take pride in the firm, suggest their own savings and the savings are implemented. Branch three: the savings exceed the peer group and are given back to customers in the form of lower prices. Branch four: the customer reciprocates and revenues rise. Branch five: further scale advantages lead to more savings per seat flown. Branch six: further customer reciprocation. Branch seven: the network builds and crowds out other, less efficient airlines. Branch eight: competitors go out of business?”
“So, in our opinion, it won’t be the on-line fraud, per se, or, heaven forbid, an airplane crash at AirAsia, that could ruin our firms, but a disingenuous response to a problem.”
Feel free to comment, share my article with friends and subscribe to my newsletter if you like my content and you want to follow me towards financial freedom.
You will obtain free access to my newsletter:
- Financial education
- A open minded and value oriented mindset
- Business and sector analysis
- A stoic and calm attitude towards the market ups and downs
No noise, only signal and high valuable contents
“Everything should be made as simple as possible, but not simpler.”
Albert Einstein
Free investing course index:
Related articles:
17. Cash Flow Statement Analysis
Disclaimer: The information contained on this website is for general information and educational purposes only. It is not intended as a substitute for legal, commercial and/or financial advice from a licensed professional.

Leave a Reply